PIP benefits are available without a finding that the other driver caused the crash. The initials stand for personal injury protection. You claim covered expenses through your own insurance. If the at-fault driver has no applicable insurance, uninsured motorist (UM) coverage may help. When that driver has insurance but too little to cover your damages, the question is underinsured motorist (UIM) coverage. You must prove fault and damages for UM or UIM.
This article is part of our Texas Car Accident Knowledge Hub. The Texas car accident claims and litigation guide explains the broader claim process.
Compare PIP, MedPay, UM and UIM
| Coverage | Main purpose | What to check |
|---|---|---|
| PIP | Specified medical expenses, income loss and qualifying household services, regardless of fault | Covered person, benefits, proof, limit and any written rejection |
| MedPay | Medical and funeral expenses under the contract, regardless of fault | Who is covered, eligible expenses and time limits; no lost-wage benefit |
| UM | Covered damages caused by an uninsured driver | Fault, damages, uninsured status and any unidentified-driver requirements |
| UIM | Covered damages beyond the at-fault driver's available liability coverage | Fault, damages, other insurance, policy limits and settlement conditions |
The Texas Department of Insurance auto insurance guide describes these coverages. Collision coverage serves a different purpose: damage to the insured vehicle under its terms. It does not replace an injury claim.
What Texas PIP pays
Texas requires $2,500 of PIP per person unless the named insured rejects the coverage in writing. Your declarations may show more if you bought a higher limit. The limit is shared by the benefits payable under PIP, rather than a fresh amount for each kind of loss.
Lost wages are one reason to distinguish PIP from MedPay. PIP pays 80%; MedPay pays no wage benefit. The Office of Public Insurance Counsel’s comparison explains that difference. Check your wage records separately from your treatment bills when you prepare the claim.
The expenses eligible for PIP appear in Insurance Code sections 1952.151–1952.156. Reasonable and necessary medical and funeral expenses must arise from the accident and be incurred within three years. For someone earning income, the statute provides an income-loss benefit. For an eligible person who was not an income producer, it instead addresses necessary services replacing household work. That provision excludes income-producing services normally performed for pay.
Here is a hypothetical PIP calculation. The policy has a $2,500 limit. For the calculation only, assume the person is covered and both losses qualify:
- Medical expenses: $1,000.
- Wage benefit: $2,000 × 80% = $1,600.
- Combined request: $2,600, which is $100 above the $2,500 limit.
The same limit applies to both benefits together. You do not get a separate $2,500 allowance for each. The insurer will still need proof, and the policy terms apply.
A wage claim needs more than a statement that you missed work. Put the missed shifts beside your pay records and the medical restrictions that kept you from working. An employer may be able to confirm the hours and rate of pay. If you claim replacement household services, keep the invoices and a description of the work. Those records should explain why the injury left you needing help.
Does PIP require proof that another driver caused the crash?
No. You do not have to win the argument about fault before seeking PIP benefits. You do have to show that the accident and claimed expenses or losses fall within the coverage. Send the supporting records even if the drivers disagree about the collision.
When should PIP benefits be paid?
Section 1952.156 provides for periodic payment as claims arise, no later than 30 days after the insurer receives satisfactory proof of the claim. That is not an unconditional deadline running from the crash date. Keep a copy of what you submitted, when it was received and any request for additional proof. Ask the insurer to identify what it says is missing.
Obtain the policy and rejection documents
Your insurance card will identify the carrier, but it will not settle a PIP or UIM coverage question. Ask for the declarations, the complete policy, its endorsements and any signed rejection forms. “Full coverage” is too imprecise to rely on. You need the actual limits and the contract’s definition of an insured person.
PIP and UM/UIM have separate statutory provisions for written rejection by the named insured. A prior rejection may carry forward to a renewal in circumstances specified by the statute. If the carrier says either coverage was declined, request the document and have its application to this policy reviewed. Do not assume that a missing new signature at every renewal establishes coverage. See sections 1952.101 and 1952.152.
A passenger should bring household auto insurance information, even if someone else owned the car involved in the wreck. Explain any delivery, rideshare or business use. Also identify the owner and whether the driver had permission. Counsel can then work through the potential policies one at a time, recording the carrier, coverage period, insured person and limits. Mark an unanswered coverage question as unanswered until the documents resolve it.
Why a UIM claim needs liability and damages proof
A small liability policy is only part of the UIM analysis. You must also establish damages you are legally entitled to recover from the other driver. Section 1952.106 limits benefits to the policy's coverage and requires a reduction for amounts recovered or recoverable from the underinsured vehicle's insurer. A demand for the full UIM limit therefore needs more than a copy of the other carrier's settlement offer.
For a hypothetical example, take a passenger whose medical bills exceed the other driver’s liability limit. A relative’s policy lists UIM, so the passenger brings it to counsel. The first question is whether the passenger falls within that policy’s definition of an insured. If so, there is still work to do: connect the treatment to the collision, establish the recoverable losses and account for the other insurance. Merely adding the two policy limits would skip those questions. This example describes no actual firm case.
UIM litigation often begins with a dispute over what the injured person is entitled to recover. The judgment requirement is addressed in Brainard v. Trinity Universal Insurance Co.; Allstate Insurance Co. v. Irwin allows the insured to seek a declaration of that entitlement directly against the UIM insurer.
For related extracontractual claims, In re State Farm (2025) discusses In re USAA General Indemnity Co. and the limits on discovery before UIM entitlement is resolved.
The parties can still negotiate a settlement. If negotiations fail, counsel needs to determine what must be proved next. An offer you consider too low does not, on its own, establish bad faith or a presently actionable breach of the duty to pay UIM benefits.
Review a liability release before signing
Before you sign paperwork that arrives with a car-repair check, send the offer, unsigned release and every attachment to your lawyer. The release could cover your injuries too. Ask your lawyer to identify:
- Each person or company the release protects.
- The injury, property-damage or other claims it would end.
- Any wording that needs correction to reflect the agreed settlement.
Consent is another issue to resolve before taking the liability settlement. Your UIM contract may prohibit settlement without the carrier’s consent, since releasing the driver can affect the carrier’s subrogation rights. Ask counsel to check the clause and secure any necessary consent in writing. The court discusses consent and prejudice in footnote 2 of In re State Farm. Already signed? Give counsel the release and correspondence rather than assuming UIM coverage has been lost or preserved.
Several injured people may be competing for the same liability limit. Ask how much of that limit is available for your proposed settlement and what happens to the other claims. Do not sign while assuming that the entire limit is reserved for you.
A practical claim checklist
- Give notice. Report through the channels required by the applicable policy and retain the claim number and confirmation.
- Preserve crash evidence. Keep photographs, witness details, recordings and the crash report. Do not change or discard earlier statements.
- Document losses. Collect itemized bills, treatment records, work restrictions, earnings records and receipts for claimed services.
- Track requests. Save letters, attachments, submission receipts and deadlines. Ask for the policy provision supporting a denial or partial payment.
- Review each settlement. Obtain advice about release scope, required consent, deductions and the claims that would remain.
Before responding to a request for a recorded statement, send your lawyer the request, the insurer’s name and the adjuster’s contact information. Preparing a response to your own insurer may involve a contractual cooperation duty. The other driver’s insurer is investigating its insured’s liability. Counsel can explain what the particular request requires before you give a statement or sign a form. Refusing every request without advice could jeopardize your own coverage.
Payments, reimbursement and estimated net recovery
Track who paid each bill and under which coverage. A PIP payment does not answer whether a health plan or another payer has a valid reimbursement claim. PIP has its own statutory restriction on subrogation, with a specified exception. Medicare obligations, hospital liens, workers’ compensation claims and health-plan demands need their own legal and document review. Calling all of them “medical liens” obscures those differences.
The amount offered is not necessarily the amount you will receive. Ask for a written calculation showing the fees, expenses and valid obligations to be paid from it. A proposed reduction in a medical balance should be identified as proposed until it is agreed. Counsel can also explain the likely costs and collection risks of continuing the case. Your lawyer can advise you; you decide whether to accept the settlement.
Deadlines deserve their own review
The personal injury filing period is generally two years from accrual (Civil Practice and Remedies Code section 16.003). A lawyer should calculate your date and address diligence in service, then check the PIP, UIM, contract and notice deadlines separately. Negotiations ordinarily do not extend limitations, even if the adjuster is still considering the claim.
The six-month notice provision in Texas Tort Claims Act section 101.101 deserves immediate attention if a government vehicle or entity was involved. Counsel must consider immunity, the statutory exceptions and any applicable city requirements. Mention a child’s age, incapacity, death or estate at the first consultation too, because those facts can affect the dates. While counsel checks them, continue gathering and preserving the evidence.
Questions clients often ask
Does my own insurer become involved if I was not at fault?
Yes, your own coverage may matter. Tell counsel what insurance you have; do not leave it out because you believe the other driver caused the wreck. PIP and MedPay, for example, do not depend on proving that driver’s fault.
Does a hit-and-run automatically qualify for UM benefits?
No. If the driver or owner cannot be identified, Insurance Code section 1952.104 includes a requirement of physical contact. Save any footage and witness details that can help show what happened. Counsel still has to check the applicable policy and reporting requirements before assessing UM coverage.
Can I dispute my insurer's offer?
You can question the offer and obtain advice about disputing it. Ask for the carrier’s reasoning: is it disputing fault, the treatment, the amount of loss or coverage itself? The answer helps counsel decide what evidence and procedure the claim needs.
Do several policies guarantee a larger recovery?
No. You might not qualify as an insured under every policy you identify. Even where you do, the contracts, proven damages and applicable adjustments may prevent adding all the limits together. Have each potential source checked before relying on it.
How specialized trial preparation can help your claim
Aaron A. Herbert is Board Certified in Personal Injury Trial Law by the Texas Board of Legal Specialization. The firm's published background describes its trial experience, and its case results provide information about past recoveries. Previous outcomes do not guarantee a similar result. Preparation must address the evidence, coverage and disputed questions in your case.
For a coverage review after a Texas crash, request a free consultation with The Law Firm of Aaron A. Herbert, P.C. or call 214-200-4878. Bring your policies, claim correspondence and any proposed release. Tell the office about approaching deadlines and ask who would handle the work and how fees and expenses are addressed.
Attorneys considering a referral can reach the firm through the contact page. Until the firm accepts the case, confirm who is attending to approaching deadlines. An inquiry by itself does not create an attorney-client relationship.
Legal sources and related reading
- Texas Department of Insurance: Automobile insurance guide.
- Office of Public Insurance Counsel: PIP versus MedPay.
- Texas Insurance Code chapter 1952.
- Allstate Insurance Co. v. Irwin, 627 S.W.3d 263 (Tex. 2021).
- In re State Farm Mutual Automobile Insurance Co., No. 23-0755 (Tex. 2025).
- Texas Rules of Evidence and Texas Rules of Civil Procedure for counsel evaluating proof and litigation procedure.
- Texas car accident claims and litigation guide and Texas Car Accident Knowledge Hub.
This article provides general information about Texas law. Application depends on the facts, policy, court orders and law governing the particular claim. Hypothetical examples are illustrations rather than reported firm cases.
ABOUT THE ATTORNEY
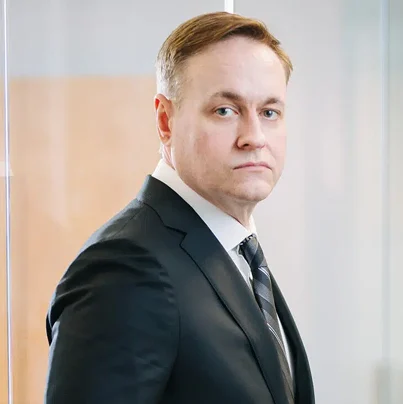
Aaron A. Herbert
Founding Attorney
Board Certified in Personal Injury Trial Law
Aaron founded The Law Firm of Aaron A. Herbert in 2010 to focus on developing each client's case and seeking its maximum value. For over a decade, he has represented people seriously injured in major accidents and industrial catastrophes, pursuing trial verdicts and settlements while working to reduce the stress of litigation.
Education
- Texas A&M University · B.S., Criminal Justice, 1999
- University of Oklahoma College of Law · J.D., 2002; graduated in the top of his class
Trial experience & approach
Aaron earned numerous jury verdicts at boutique personal injury litigation firms. According to his biography, he spent a year as the top-earning litigation attorney at a firm that frequently appeared in verdict searches as having one of the highest numbers of trial wins in Texas. At another Dallas personal injury firm, he moved from managing pre-litigation attorney to managing litigation attorney over seven years as the firm grew into one of Dallas's largest personal injury firms.
His biography describes a reputation as one of America's most aggressive trial lawyers, with noteworthy recoveries from judges and juries and substantial pretrial settlements. Most of those settlements included confidentiality agreements requested by the defense. Aaron has said the recoveries were justified by the injuries and losses involved, which no amount of money could make someone choose to experience.
His approach combines passion, preparation, persistence and courtroom imagination. He believes a well-supported, engaged and motivated team working cooperatively helps deliver strong representation, with the goal of achieving the best possible result for every client.
Dallas roots, military service & publication
Born and raised in Dallas, Aaron enlisted in the United States Marine Corps after high school and later received an Honorable Discharge. He completed his university and law degrees after his military service and became a lifelong Sooners football fan in law school.
Publication: “Litigating Dog Bite Cases,” Texas Dog Law Seminar, Dallas, 2009.
Professional affiliations & recognition
Professional affiliations and recognition listed in Aaron’s biography:
- State Bar of Texas
- American Bar Association
- Association of Trial Lawyers of America (now American Association for Justice)
- Texas Trial Lawyers Association
- Dallas Trial Lawyers Association
- Dallas Bar Association
- Tarrant County Bar Association
- Million Dollar Advocates Forum
- The National Trial Lawyers – Top 100 Trial Lawyers