Read the proposed release before deciding what the offer is worth to you. Then discuss the medical evidence, disputed fault, likely take-home amount, and cost and risk of continuing with your lawyer. The actual documents and remaining uncertainties should guide that discussion.
Read the offer and release together
Compare the payer and amount in the offer with the release. Read every named person and claim. Injury and property damage may be settled together, while a claim against another defendant may remain. Have the effect on other claims or coverage explained before signing.
Ask what the indemnity language would require if somebody made a later demand against the other side. It may place an obligation on you. Have that explained before signing, along with terms about unknown injuries, future treatment, other insureds, liens and confidentiality. Note both the return deadline and the date payment is due.
If the release says more than you thought you were agreeing to, stop and have that difference addressed in writing. A phone explanation may leave the actual language unchanged. After the claims described in the agreement are settled and released, obtaining more money for them may no longer be possible—even if your understanding of the deal was narrower. Ongoing symptoms make that discussion all the more pressing.
Evaluate the evidence and disputed issues
What exactly does the insurer dispute? For conflicting accounts of a turn, photographs, witnesses or vehicle data may help. A claim that your back condition predates the crash calls for different proof: the medical history and an appropriate medical opinion. More detail about the intersection may do little to answer that medical question.
Ask what the file already contains and what is missing. A witness who has not been interviewed, an uncollected employment record, or an unavailable scan is not the same as evidence that has been reviewed and found unhelpful. Find out whether the missing material can still be obtained and whether it is likely to change the evaluation.
Fault allegations deserve careful attention because Texas law can reduce—or bar—a recovery. For cases within Civil Practice and Remedies Code Chapter 33, a claimant’s percentage of responsibility reduces the damages recoverable, and § 33.001 bars recovery if the percentage exceeds 50. The adjuster’s proposed percentage is not a judicial finding. Have counsel explain what evidence could support it and what evidence cuts the other way.
There are two sets of proof to discuss. One concerns responsibility for the collision. The other concerns the losses: which treatment the injury required, reasonable medical costs, earnings lost, and any supported future need. Even where the driving evidence is strong, a particular treatment may be disputed. And a substantial bill cannot tell you who caused the collision. Ask how the best evidence—and the weaknesses—look on each issue.
Compare the gross offer with the likely net
The draft distribution shows how the gross offer becomes your estimated share. It should subtract the fee under your signed agreement, itemized expenses and valid medical or benefit repayments. Check whether the payoff figures are confirmed. A provider may still reject a requested reduction.
If money will be held while a repayment dispute is resolved, get an explanation of the amount and the next step. Do not budget on the assumption that every requested reduction will be granted. A current payoff letter is more useful than a balance copied from an old email.
For a Medicare beneficiary, accident-related treatment may involve conditional payments that Medicare seeks to recover after a liability settlement. CMS guidance on demand calculations describes options for updated information and certain calculations before settlement when the requirements are met. Other health plans and providers have different rules. Have the applicable process checked rather than applying one program’s figures or procedures to another.
Account for what happens if you continue
Ask your lawyer to describe the next actual step, not simply the possibility of a trial. Would it be obtaining a medical opinion, taking a deposition, or attending mediation? What would it cost, how long might it take, and what useful information could it produce? Further work can change a valuation in either direction.
There may be depositions to attend, hearings to prepare for, or further expert opinions to obtain. Those steps take money and time, sometimes including time away from work or family. They may be justified by the claim, but you should know what is likely to be required. A prediction of success is still a prediction. Include the possibility of an adverse result when weighing the alternatives.
A doctor’s recommendation for further care is different from a procedure mentioned only as a possibility. Find out which the record actually supports. The first should not be overlooked, and the second should not be presented as certain. Either way, discuss what worsening symptoms would mean under the proposed release. The settlement may remain final even though your condition changes.
Questions to ask before responding
Bring three things to the discussion: the release, your treatment questions and the draft distribution. Work through who and what would be released, the future-care evidence, disputed fault and missing records.
Which payoffs are still unconfirmed? How much would be left for you? Put that estimate beside the cost of the next litigation step and the evidence it could produce. Confirm the expiration date and the response required.
Your lawyer should check the deadline in the written offer. Ask about unclear terms before it expires; asking a question does not necessarily buy extra time.
Make a documented decision
Make a note of what remained uncertain when you reviewed the offer. Keep it with the release and distribution estimate. If a revised offer arrives, check those terms again as well as the new amount.
You do not have to pretend to understand a term you find confusing. Ask the lawyer handling the matter to explain it, including how it affects your choice. The purpose of this review is an informed decision about your own claim. Neither pressure to finish nor a general checklist can make that decision for you.
Related reading
See also how much you’ll take home from a Texas injury settlement and when trial experience matters even though most cases settle.
For the broader explanation of case value, visit the Texas Injury Claim Value Knowledge Hub.
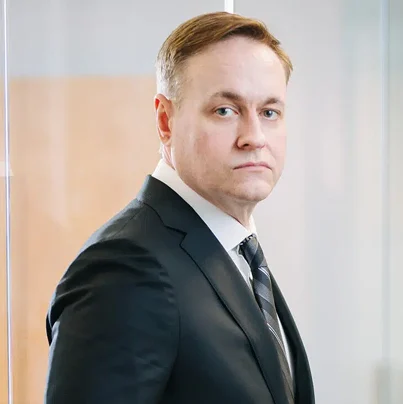
Founding Attorney
Aaron A. Herbert is a Texas attorney, Board Certified in Personal Injury Trial Law by the Texas Board of Legal Specialization.
For over a decade he has shown an unwavering commitment to clients who were seriously injured by major accidents and industrial catastrophes. During that time he has earned the reputation as one of America’s most aggressive trial lawyers by achieving noteworthy recoveries from judges and juries, as well as substantial settlements prior to trial, the majority of which contained negotiated confidentiality agreements at the request of the defense. When asked about these cases, Mr. Herbert has said that each case not only justified the recovery level, but that no one would trade places with any one of these victims in return for any amount of money, once they know the facts and severity of the injuries and tragedy involved. According to Mr. Herbert, “there can be no substitute for passion, preparation and persistence in the practice of law.” He is known not only for this tenacious preparation, but also for his imagination in the courtroom. He is passionate and persistent in seeking to obtain the maximum case value for each individual client at trial or through settlement, while reducing the stress of litigation on his clients.
Born and raised in Dallas, Texas, Mr. Herbert enlisted in the United States Marine Corps after high school and later received an Honorable Discharge. After the Marines, he obtained a Bachelor of Science in Criminal Justice from Texas A&M University, then a Juris Doctorate from the University of Oklahoma College of Law. There he graduated in the top of his class and became an eternal Sooners Football fan. Aaron has worked as a zealous advocate for injured clients at several boutique personal injury litigation firms where he amassed numerous jury verdicts. After spending a year as the top earning litigation attorney at a firm that frequently tops verdict search as one with the highest number of trial wins in Texas, Aaron accepted a position as the managing pre-litigation attorney at another Dallas personal injury firm. Over the next seven years he transitioned to the managing litigation attorney, and that firm grew to one of the largest personal injury firms in Dallas. In 2010 he formed the Law Firm of Aaron A. Herbert, to get back to a focus on developing each individual case and maximizing case value for each client.
Mr. Herbert practices law with the belief that a well taken care of, highly engaged and motivated team of employees working in a cooperative team environment will result in superior representation and great results for the firm clients. He believes in always setting a goal of achieving the best possible results for each and every client.
Education
- Texas A&M University (B.S. Criminal Justice, 1999)
- University of Oklahoma College of Law (J.D., 2002)
Professional Associations
- Licensed to practice in Texas (2002)
- Board Certified in Personal Injury Trial Law, Texas Board of Legal Specialization (2008)
Publications
- Litigating Dog Bite Cases, Texas Dog Law Seminar, Dallas 2009
Member
- State Bar of Texas
- American Bar Association
- American Trial Lawyer Association
- Texas Trial Lawyers Association
- Dallas Trial Lawyers Association
- Dallas County Bar Association
- Tarrant County Bar Association
- Million Dollar Advocates Forum
- National Trial Lawyers – Top 100 Trial Lawyers
Texas Bar #24036761 · The Law Firm of Aaron A. Herbert, P.C. · Dallas, Texas
General information, not advice to accept or reject a particular offer. Review the actual agreement and case evidence with your lawyer.